NinjaTrader Automated Trading by Algo Futures Trader

hybrid algorithmic automated futures trading for prop firm traders, day & swing traders

🚀 Get Started FREE
  • 🚀Get Started FREE
  • NinjaTrader
  • Get Funded
  • Trading Servers
  • Pricing
  • blog
  • Help

NinjaTrader Fully Automated Futures Trading for Prop Firm Accounts

July 27, 2026 by AFT

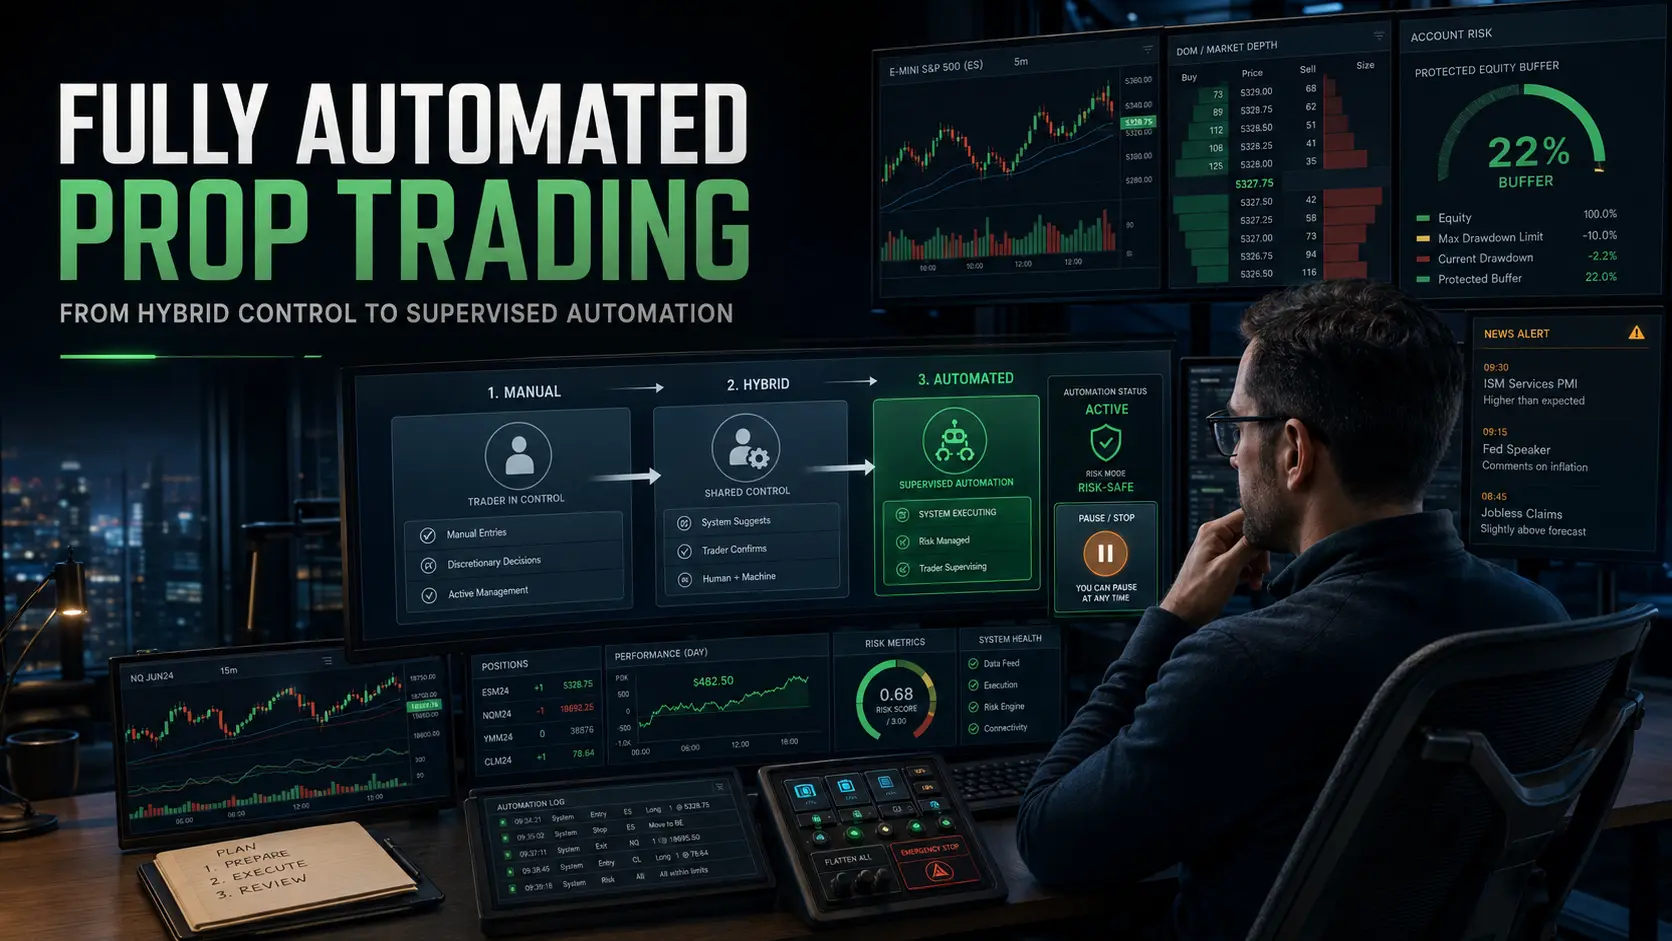
Fully automated prop-firm trading progressing from manual through hybrid control to supervised AFT automation
Progress from manual and Hybrid Algo Trading to supervised AFT automation with account-buffer protection, market alerts and operator risk controls.

Fully Automated Trading Prop Firm Accounts: How to Progress from Hybrid to Full Automation

Fully automated trading for prop firm accounts is possible with Algo Futures Trader (AFT), but the professional pathway is not to activate a universal trading robot and hope it survives. The safer and more adaptable approach is to begin with Hybrid Algo Trading, validate each element of the trading process and progressively increase automation until you reach the level appropriate for your prop firm, account rules, instrument and risk tolerance.

Can ATS Be Used for Fully Automated Prop-Firm Trading?

Yes. ATS provides purpose-built automated systems and risk controls for prop-firm evaluations, simulated-funded accounts, funded accounts and live brokerage trading. However, every deployment must be configured around the selected prop firm, account type, drawdown allowance, consistency rules, permitted automation, instrument, position size and trading session.

The objective is not uncontrolled set-and-forget trading. A professionally operated AFT system may automate approximately 90% to 95% of the practical trading process while retaining the operator controls needed to pause, restrict or exit trading when market or account conditions become unsuitable.

Automation should be earned in small, measurable steps. Begin with Hybrid Algo Trading and increase automation only after each stage has been tested, understood and validated.

Why Prop-Firm Accounts Require a Different Approach

A prop account may advertise a large nominal account size, but the amount that matters is the permitted drawdown. In practical risk terms, the drawdown allowance is the real account.

A trading system can be profitable over a long period and still breach a prop-firm account during an ordinary losing sequence. Trailing drawdown, daily loss limits, consistency rules, restricted trading periods and maximum contract limits can prevent a system from remaining active long enough for its statistical edge to develop.

Successful automated prop-firm trading therefore requires more than profitable signals. It requires a complete operating framework covering:

  • Prop-firm rules and permitted automation.
  • Maximum daily and total account risk.
  • Position sizing and contract limits.
  • Expected and worst observed drawdown.
  • Trading-session and instrument selection.
  • News, volatility and liquidity controls.
  • Contract rollover procedures.
  • Platform, connection and order monitoring.
  • Clear pause, exit and emergency-stop rules.

The Progressive Path from Hybrid to Fully Automated Trading

Step 1: Define the Prop-Firm Operating Rules

Begin by documenting the exact rules for the intended evaluation or funded account. Confirm whether automated trading, trade copying and unattended operation are permitted. Record the drawdown calculation, daily loss limit, consistency requirement, maximum position size, restricted news periods and any rules covering overnight or weekend positions.

Prop-firm policies can change, so these conditions should be verified directly with the firm before deployment and reviewed regularly.

Step 2: Start with an Official ATS Baseline

AFT provides turnkey systems and official baseline settings that can be assessed in Simulation, Market Replay and walk-forward operation. ATS automated Workspace 5 includes baseline models such as DSFG USAR, DSFG USAR GAP and WSFG USAR.

A baseline is a professional starting point, not a guaranteed universal configuration. It must be measured against the intended instrument, session, account rules and current market phase before it is considered for prop-firm deployment.

Step 3: Use Manual Entry with Automated Trade Management

The first practical stage is normally manual trade permission combined with automated order and exit management. The trader decides whether the setup and market conditions are suitable, while AFT controls the stop loss, profit targets, partial exits, trailing logic and other repetitive trade-management tasks.

This stage allows the trader to learn the signals and observe how the system behaves without surrendering control of trade selection.

Step 4: Progress to Hybrid Automated Entry and Exit

Once the trader understands the system, automated entry can be introduced under controlled conditions. The operator can enable long-only, short-only or two-way trading according to market direction, session structure and higher-timeframe bias.

AFT handles execution with machine speed and consistency, while the trader retains authority over when the system is permitted to trade. This removes much of the emotional and mechanical workload without removing human adaptability.

Step 5: Add Multi-Timeframe and Market-Context Controls

The next stage combines AFT automation with multi-timeframe confirmation, AlphaWebTrader market intelligence and AI Copilot support. The system can manage individual trades automatically while the operator assesses the wider trading environment.

At this stage, the trader should maintain statistics for each instrument, direction, setup, session and market phase. Automation should only be increased when the measured results remain compatible with the prop account’s limited drawdown allowance.

Step 6: Build an Account Buffer Before Increasing Automation

A profitable evaluation or funded account should not automatically trigger larger position sizes or less supervision. The first priority is to build a buffer between the current account equity and the applicable breach threshold.

This buffer gives the system more capacity to absorb normal losing trades, slippage and changing market conditions. It does not make the account safe or eliminate the possibility of failure. The required buffer must be based on the firm’s rules, the system’s observed drawdown, the position size and the operator’s risk limits—not an arbitrary percentage or fixed dollar target.

Until a suitable buffer exists, the trader may choose to maintain smaller size, restrict trade frequency and continue using hybrid approval rather than enabling wider automated operation.

Step 7: Increase Automation One Control at a Time

Automation can now be expanded progressively. The operator might first automate entries during one defined session, then automate directional selection, trade limits or additional approved setups. Only one material change should be introduced at a time so its effect can be measured.

If the equity curve, drawdown or execution begins to deviate materially from the validated baseline, automation should be reduced and the system returned to Simulation or hybrid control for review.

Step 8: Operate at 90% to 95% Automation with Human Oversight

The advanced objective is not necessarily 100% unattended trading. ATS can automate approximately 90% to 95% of the practical process while preserving a critical operator layer for market, account and technical risk.

The software can identify signals, place orders, manage positions, enforce trade limits and execute exits. The operator remains responsible for activating the correct system, confirming the market environment, supervising connectivity and intervening when conditions fall outside the validated operating plan.

When Should an Automated Prop Trading System Be Paused?

A fully automated futures trading system should not continue merely because the platform is running. The operator must be ready to pause new entries, reduce risk or exit positions when predefined conditions occur.

  • Abnormal price skew: Price movement, volatility, spreads or liquidity no longer resemble the conditions used to validate the system.
  • Major scheduled news: High-impact economic releases, central-bank decisions or other events can generate gaps, slippage and rapid reversals.
  • Unexpected geopolitical news: Breaking geopolitical developments can change correlations, liquidity and directional behavior without warning.
  • Exchange holidays: Shortened sessions and reduced participation can produce irregular volume and price action.
  • Contract rollovers: Volume migration between futures contracts can affect liquidity, indicators, signals and execution.
  • Technical events: Data interruptions, connection instability, platform problems, rejected orders or account synchronization errors require immediate attention.
  • Risk-limit proximity: Automation should be restricted or stopped before the account reaches its daily or total loss boundary.
  • Equity-curve deviation: Results that move materially outside the expected range may indicate a changed market phase, configuration problem or declining system edge.

Price-skew alerts, news intelligence and automated risk controls help identify these conditions, but the operator remains responsible for the final decision to continue, pause or exit.

Hybrid Algo Trading Is the Fastest Route to Higher Automation

It may appear faster to begin with full automation, but traders often progress more effectively by learning the system through controlled Hybrid Algo Trading. This reveals how signals, entries, exits and risk controls interact in live market conditions before the account depends on them completely.

The ATS model combines three complementary strengths:

  • Trader judgment: Determines market suitability, direction, risk and permission to trade.
  • AFT machine execution: Provides speed, precision, consistency and emotion-free order management.
  • AI Copilot intelligence: Supports analysis of market context, alerts, news, risk conditions and operating decisions.

Automation can then be increased according to demonstrated competence and measured results. Some traders may remain at 50% to 80% automation because that provides their preferred balance of control and efficiency. Others may progress toward 90% to 95% automation with active supervision.

A Practical Automated Prop-Firm Trading Checklist

  1. Confirm that the prop firm permits the intended form of automation.
  2. Calculate the effective drawdown allowance rather than relying on the advertised account size.
  3. Select one instrument, one trading session and one official ATS baseline.
  4. Configure daily loss, position-size, trade-frequency and account-level limits.
  5. Test in Simulation, Market Replay and walk-forward market conditions.
  6. Begin with manual permission and automated trade management.
  7. Introduce automated entries only after understanding the signals and exits.
  8. Measure win rate, risk-reward, drawdown, losing sequences, slippage and equity-curve deviation.
  9. Use conservative size when progressing into an evaluation or funded account.
  10. Build an account buffer before expanding position size or automation.
  11. Define rules for price skew, news, geopolitical events, holidays and rollovers.
  12. Monitor platform, connection, orders and account synchronization.
  13. Pause or reduce automation whenever results move outside the validated operating range.

Frequently Asked Questions

Can AFT trade a prop-firm account automatically?

Yes. AFT supports automated entry, automated trade management and fully automated trading modes. The configuration must match the selected prop firm’s rules, instrument, account limits and permitted automation conditions.

Is fully automated prop trading completely unattended?

It should not be treated as unattended set-and-forget trading. ATS may automate approximately 90% to 95% of the practical process, but an operator should remain available to supervise risk, news, market conditions, contract rollovers and technical events.

Should I begin with fully automated trading?

The preferred ATS pathway is to begin with Hybrid Algo Trading and increase automation through small, measurable steps. This allows you to understand the system, establish your own statistics and identify problems before they threaten a prop account.

How large should the prop-account buffer be?

There is no universal figure. The required buffer depends on the prop firm’s rules, the system’s observed drawdown, position size, trade frequency and the trader’s risk limits. A buffer reduces immediate pressure but cannot guarantee that an account will survive future losses.

Can automation guarantee an evaluation pass or payout?

No. Automated and hybrid trading systems can lose money, and no software can guarantee an evaluation pass, funded account or payout. Results depend on market conditions, system configuration, risk control, execution and operator decisions.

How to Get Started with Automated Prop-Firm Trading

The most adaptable route is to start with AFT turnkey workspaces, learn the ATS Hybrid Algo Trading Methodology and progressively increase automation as your experience, statistics and account buffer develop.

Review the complete answer to Can ATS be used for fully automated prop-firm trading?, or explore the ATS trading pathways for assisted onboarding, full-featured AFT access, Zero-to-Hero orientation and the tools required to develop your own hybrid or automated prop-firm trading operation.
Filed Under: AFT8, Algo Futures Trader, automated futures trading, ninjatrader automated trading, prop firm trading Tagged With: AFT, algo futures trader, Fully Automated Trading, Futures Trading Automation, hybrid algo trading, ninjatrader automated trading systems, Prop Firm Accounts, risk management

The Rise and Fall of Swing Trading and Day Trading: How Intraday Algorithms Rebuilt the Futures Market

July 20, 2026 by AFT

Traditional swing-trading desk transitioning into high-frequency algorithmic futures trading and institutional market networks
The transition from overnight swing-risk desks to high-turnover electronic and algorithmic futures markets

Futures volume accelerated as electronic day-trading desks and autonomous market-making algorithms began recycling the same capital repeatedly within the session. The market did not necessarily gain an equivalent amount of long-term or overnight risk capital: it gained turnover.

For much of the twentieth century, the visible market was also the market. A trader on an exchange floor, a bank dealer on a telephone or a proprietary desk watching a price screen could participate directly in price discovery. Day traders competed through local knowledge, order-flow awareness, judgment, and speed of response. Swing traders attempted to capture movements lasting several days or weeks.

That structure has been transformed. The modern market is a network of public exchanges, broker-dealer internalisers, alternative trading systems, interdealer platforms, bank liquidity pools, request-for-quote systems, and bilateral over-the-counter relationships. Much of the activity linking those venues is generated, routed, priced, hedged, and cancelled by software.

The pivotal change became visible around 2005–2006. Futures volume was rising much faster than the positions left open at the end of the day. Screen-based proprietary desks, electronic market makers, and early automated systems were taking over functions previously performed by floor locals and slower discretionary desks. The human day-trading desk was itself becoming an algorithm.

The result is not the literal death of day trading or swing trading. It is the transfer of the fastest part of the business from human judgment and overnight position-taking to high-turnover, tightly controlled, and increasingly machine-managed inventory.

The Apparent Paradox: Less Money, but More Futures Volume

The paradox disappears once four different measurements are separated:

MeasureWhat It RecordsWhat It Does Not Record
Trading volumeHow many contracts changed hands during a periodHow much exposure remained after the trades were closed
Open interestContracts still outstanding at the end of the trading dayHow many times positions were opened, transferred or closed intraday
Margin or performance-bond collateralAssets pledged to support the risk of open positionsThe full notional value of the contracts or total daily turnover
Notional valueThe referenced economic exposure of the contracts tradedCash invested in the way market capitalisation measures equity value

A futures contract is not a share purchased for its full value. Every long is matched by a short, and both sides post only the required collateral. Volume can therefore multiply without a comparable increase in open interest or cash committed overnight.

For example, 100 swing traders who each open one contract and retain it for ten days create 100 contracts of opening volume and 100 contracts of continuing open interest. By contrast, ten intraday traders completing 50 round-trip trades each can generate 1,000 contracts of single-counted volume while finishing the session with no open interest at all. The smaller day-trading group creates ten times the recorded volume but leaves no overnight position.

Volume is activity. Open interest is standing exposure. Margin is collateral. They are related, but they are not interchangeable measures of “money in the market.”

Why 2006 Matters

CME’s 2006 annual report provides unusually clear evidence of the transition. The exchange said its record volume was driven partly by faster technology and increased use of automated trading systems. It also began allowing customer firms to connect co-located servers over high-speed fibre, with anticipated order-entry latency below one millisecond.

CME Measure20052006Change
Total annual trading volume1.048 billion contracts1.341 billion contracts+28.0%
Electronic volume on CME Globex730 million contracts956 million contracts+31.0%
Year-end open interest30.083 million contracts35.107 million contracts+16.7%
Annual volume divided by year-end open interest34.8 times38.2 times+9.7%
Cash performance bonds$579 million$506 million−12.6%
Total cash and non-cash performance-bond collateralApproximately $46.39 billionApproximately $47.78 billion+3.0%

The volume-to-open-interest calculation is a simple comparison using year-end open interest, not an official CME turnover statistic. It is included to illustrate the direction of the change.

The numbers require a precise interpretation. CME open interest did not decline in 2006; it rose. Total performance-bond collateral also rose. The cash component fell because clearing firms could use securities and investment facilities as collateral, so the decline in cash alone should not be treated as proof that total risk capital left the market.

Nevertheless, activity rose much faster than standing exposure. Annual volume increased 28%, compared with a 16.7% increase in year-end open interest. A crude turnover proxy consequently rose by almost 10% in a single year. This is consistent with a market in which capital was being turned over faster and more positions were being opened and closed during the session.

The strongest asset-level evidence came from electronic markets. CME reported that electronically traded foreign-exchange volume rose 46% in 2006 while open-outcry FX volume fell 26%. E-mini equity volume increased 25%, and electronic interest-rate volume increased 34%. The exchange explicitly associated the broader growth with technological improvements and increased use of automated trading systems.

Annual volume and open interest cannot identify every trader’s holding period. They do not prove by themselves that all swing desks were replaced by day-trading desks. Combined with the migration to Globex, faster matching, automated-system participation, incentive programmes and co-location, however, they provide strong evidence that the market’s marginal unit of activity was becoming more electronic, faster and more intraday.

How Day-Trading Desks Took Over the Overnight Swing Function

The transition occurred in stages rather than in a single overnight event:

  1. Traditional swing and dealer desks held inventory. Their economic function involved accepting price risk between customer trades, sessions or market events.
  2. Electronic proprietary desks shortened the holding period. Screen-based traders and trading arcades could enter and exit more frequently, often flattening at the end of the day.
  3. Market-making algorithms automated the day desk. Software could quote both sides, hedge related products and recycle inventory many times before a human could complete one decision loop.
  4. Risk migrated rather than vanished. Longer-term exposure remained with hedgers, asset managers, hedge funds, banks and end users, while the transfer of that risk between participants became a high-speed intraday business.

The essential shift was from earning a return by holding a directional position to earning a smaller return many times by intermediating, hedging, or arbitrage flow. The former consumes time and overnight risk capacity. The latter consumes technology, message capacity, connectivity, and operational control.

This explains how exchange volume could grow without an equivalent increase in committed capital. The contract became a reusable vehicle for intraday risk transfer rather than simply a position held until the next major price movement.

Public Futures Markets Became the Hedge Engine for Private Institutional Networks

The growth in futures volume was not generated only by traders speculating directly on an exchange. Public futures order books increasingly became the immediate hedging layer for exposures created elsewhere.

A bank may execute a private client transaction in an OTC market and hedge it in public futures. An options market maker may trade an option, hedge the resulting delta in futures and rebalance repeatedly as price and volatility change. An ETF or cash-equity desk may use index futures while it assembles or unwinds a basket. A commodity dealer may negotiate a physical contract privately and transfer price risk through exchange-traded futures.

One underlying investment or commercial decision can therefore generate several futures transactions:

  1. a client creates the original exposure in a public or private venue;
  2. a bank or dealer hedges that exposure in futures;
  3. an electronic market maker takes the other side and hedges elsewhere;
  4. an arbitrage desk links the futures price to cash, ETF, options or OTC markets; and
  5. each intermediary adjusts or closes its hedge as market conditions change.

The volume recorded by the futures exchange can rise several times, even though the original economic exposure was created only once. Futures became the high-speed public transmission system connecting slower and more private pools of institutional risk.

Public Futures AssetPrivate or Institutional Exposure Commonly Hedged
Equity-index futuresCash-equity baskets, ETFs, listed and OTC options, structured products and portfolio flows
Interest-rate and Treasury futuresGovernment bonds, swaps, mortgage portfolios, corporate debt, repo and bank rate exposure
FX futuresSpot FX, forwards, swaps, options, corporate hedges and cross-border portfolios
Energy futuresPhysical production, storage, transport, refinery exposure, OTC swaps and commodity options
Agricultural and metals futuresProduction, inventories, forward contracts, merchant books and industrial consumption
Volatility and digital-asset futuresOptions books, structured volatility exposure, spot holdings and private OTC transactions

The Central Change: Human Traders Lost the Fastest Time Horizon

A human trader and a high-frequency market maker may both open and close positions within the same day, but they are not conducting the same business.

A conventional day trader normally assumes directional risk. The trader expects price to move and attempts to profit from that movement. A swing trader does the same over a longer period, accepting overnight and event risk in exchange for a larger potential move.

A high-frequency market maker is usually attempting to quote both sides, manage inventory, preserve queue position, capture spreads or rebates, and hedge related exposure across instruments or venues. It may trade thousands of times without expressing a meaningful view on where the market should close.

This is why high-frequency trading should not be described simply as very fast day trading. It is an industrial form of liquidity provision and short-horizon risk transfer, supported by direct data feeds, co-location, specialised infrastructure, automated controls and substantial capital.

Important distinction: “Unattended” does not usually mean unmonitored. Professional systems may make individual quoting and execution decisions without human approval, but firms supervise them through exposure limits, credit controls, kill switches, surveillance and operational staff.

From the Trading Pit and Telephone to Co-location and Code

1. The Human Market

Traditional exchanges concentrated participants physically. Floor brokers represented customers, specialists or designated market makers maintained markets, and independent “locals” traded for their own accounts. In foreign exchange, government bonds, corporate debt and derivatives, bank dealers made prices over the telephone and used their balance sheets to warehouse risk.

Access was scarce. Exchange membership, physical presence, dealer relationships and timely information created an economic advantage. The trader who stood closest to the flow could react before somebody outside the room.

2. Electronic Access Expanded the Market

Nasdaq began as an electronic stock market in 1971. CME Globex launched in 1992, and the E-mini S&P 500 later became a decisive product in the migration from the futures pit to the screen. CME described electronic access as a way to remove the physical capacity limit of the pit and allow customers to trade directly through clearing firms and trading software. The NYSE introduced its Hybrid Market in 2005, combining floor-based and electronic execution.

This was initially a democratising change. Electronic platforms reduced geographic barriers, extended trading hours, improved confirmation speed and gave more participants direct access to market data and execution.

3. Market Access Became a Technology Competition

Decimal pricing, electronic communication networks, faster matching engines and the implementation of Regulation NMS changed the economics of U.S. equity trading. Spreads narrowed, liquidity fragmented across venues and the value of being physically present was replaced by the value of connectivity, data and queue priority.

By 2010, the U.S. Securities and Exchange Commission described the equity market as having moved from primarily manual trading to primarily automated trading. It identified passive market making, arbitrage, structural and directional strategies as separate forms of high-frequency activity, alongside tools such as co-location and proprietary market-data feeds.

4. The Traditional Bank Desk Was Reorganised

After the global financial crisis, regulation and balance-sheet constraints altered the dealer model. The Volcker Rule generally prohibited proprietary trading by banking entities, while retaining exemptions for genuine market-making, underwriting and risk-mitigating hedging. This did not remove bank trading desks, but it narrowed the case for holding large positions purely for the bank’s own speculative return.

Risk did not disappear. Some of it moved from traditional bank balance sheets towards non-bank principal trading firms, hedge funds, electronic liquidity providers and asset managers. Bank dealers remained central where customer relationships, credit, financing, bespoke contracts and the capacity to warehouse less-liquid positions still mattered.

5. Automation Spread Beyond Equities and Futures

The same technology moved into foreign exchange, government bonds and then selected parts of corporate fixed income. The transition was fastest in standardised, liquid instruments and slowest where trades were large, irregular, bespoke or dependent on dealer balance sheets.

Five Different Trading Businesses Often Confused as One

ParticipantTypical HorizonPrimary Economic EdgeTypical InventoryMain Risk
Human day traderSeconds to hoursDirection, session structure, discretion and selective participationNormally closed by the end of the sessionFalse signals, execution cost, leverage and emotional error
Swing traderDays to weeksTrend, macroeconomic change, catalysts, positioning and behavioural persistenceCarried overnightGaps, news, changing correlations and financing cost
Traditional dealer deskMinutes to monthsCustomer flow, relationships, credit, spread and balance-sheet intermediationManaged or hedged according to customer demand and limitsInventory, counterparty, funding and regulatory-capital risk
Institutional execution algorithmMinutes to daysCompleting a parent order while limiting market impact and benchmark slippageDetermined by the investor’s larger orderInformation leakage, adverse selection and poor scheduling
High-frequency market maker or principal trading firmMicroseconds to secondsSpread capture, queue position, rapid repricing, cross-venue hedging and scaleFrequently neutralised or tightly limitedAdverse selection, latency, model failure and a rapid liquidity shock

There are also directional algorithms, statistical-arbitrage systems and event-driven systems. “Algorithmic trading” therefore describes a method of decision-making or execution, not one strategy and not one holding period.

Public Markets and Private Trading Networks

The public quotation visible on a retail screen is no longer a complete map of the market. It may be the reference price used by other venues, but the order can execute somewhere else.

Venue TypeHow It WorksTransparencyCommon Users and Assets
Lit exchange or central limit order bookDisplayed bids and offers compete under price-and-time or similar priority rulesHigh pre-trade transparency, subject to order types and data-access differencesEquities, ETFs, futures, listed options and some digital assets
Exchange auction or block facilityOrders cross through an auction or a privately negotiated block is reported to the exchangeLimited before execution; reported according to venue rulesEquity opening and closing auctions, options auctions, futures blocks and exchange-for-related-position trades
Alternative trading system or dark poolEligible orders interact away from a registered public exchangeLittle or no displayed pre-trade interest; securities trades remain subject to reporting requirementsInstitutional equity orders, midpoint trading, blocks and selected fixed-income instruments
Wholesaler or dealer internaliserA broker-dealer executes against its own liquidity or matches flow internallyPrivate before execution, with applicable post-trade reportingRetail equities and options; bank activity in FX, bonds and derivatives
Single-dealer platformOne bank or liquidity provider streams prices directly to approved clientsPrivate and relationship-basedForeign exchange, rates, credit and structured products
Multi-dealer or request-for-quote platformA customer requests or receives prices from several dealersParticipants see selected quotes; the wider market may see only post-trade dataGovernment and corporate bonds, FX, swaps and institutional derivatives
Interdealer broker networkDealers and principal trading firms trade with one another, often anonymouslyWholesale access with limited public pre-trade visibilityGovernment bonds, FX and interest-rate products
Bilateral OTC or voice marketTwo parties negotiate price, size, credit and contract terms directlyPrivate negotiation with asset-specific reportingLarge or bespoke FX derivatives, bonds, swaps, physical commodities and structured trades
Decentralised protocol or automated market makerSmart contracts match orders or price liquidity pools under programmed rulesPublic blockchain records, but execution conditions differ from an exchange order bookDigital assets and tokenised instruments

Private does not necessarily mean secret or unregulated. It usually means that trading interest is not displayed to the whole market before execution, access is restricted, or the transaction is negotiated bilaterally. Post-trade publication, regulatory reporting and clearing obligations depend on the asset and jurisdiction.

As of May 2026, the SEC continued to maintain a formal list of regulated alternative trading systems. In a June 2026 proposal, the Commission also noted that U.S. equity fragmentation now reflects both a proliferation of displayed venues and the division of activity between exchanges and off-exchange trading. The modern equity market is therefore public and private at the same time.

Which Asset Types Are Most Automated?

The governing rule is straightforward: automation is strongest where products are standardised, continuously traded, data-rich and easy to hedge. Human and dealer intermediation remain stronger where instruments are heterogeneous, infrequently traded, credit-sensitive or negotiated in large size.

Asset TypeMain Price-Formation VenuePrivate or Institutional LayerDegree of Short-Horizon AutomationWhere Humans Still Matter
Large-cap equities and ETFsFragmented public exchange order booksATSs, dark pools and wholesalersVery highPortfolio decisions, catalysts, block execution and longer-horizon positioning
Equity index, interest-rate and major FX futuresCentralised exchange order booksBlocks, spreads and exchange-for-related-position facilitiesVery high in the most liquid contractsDirectional risk, roll management, event interpretation and less-liquid maturities
Energy, metals and agricultural futuresExchange order booksBlocks, physical-market relationships and OTC hedgesHigh in benchmark contracts but uneven across productsPhysical supply, location, quality, seasonality and commercial hedging
Listed optionsMultiple exchange order books and auctionsDealer and wholesaler liquidity, including complex-order mechanismsVery high in quotation and hedgingVolatility views, structure selection, large orders and complex risk transfer
Spot FX and FX derivativesDecentralised OTC dealer and electronic venuesSingle-dealer platforms, multi-dealer platforms, internal pools and voice tradingHigh in liquid spot pairs; mixed in derivativesLarge trades, credit relationships and bespoke forwards, swaps and options
Benchmark government bondsElectronic interdealer and dealer-to-client platformsInterdealer networks, RFQ systems and bilateral dealer booksHigh in on-the-run securities and related futuresOff-the-run issues, balance-sheet capacity, blocks and relative-value positioning
Corporate and municipal bondsDealer-to-client RFQ and bilateral OTC marketsDealer inventories, institutional platforms and relationship networksModerate and highly unevenCredit analysis, finding liquidity, negotiation and large or unusual issues
OTC swaps and structured derivativesElectronic execution where mandated or practical, otherwise bilateralBanks, swap execution facilities, interdealer brokers and clearing networksHigh for standardised pricing; lower for bespoke structuringCredit, collateral, legal terms, structuring and balance-sheet use
Digital assetsCentralised exchange order books and on-chain protocolsOTC desks, internal market makers and private liquidity relationshipsVery high but fragmented across venuesCustody, venue selection, protocol risk and longer-horizon thesis

The differences are visible in official research. A CFTC study of CME data found extensive automation across futures, with the greatest presence in liquid FX, equity-index and interest-rate products, while physical commodity contracts retained more manual participation. In U.S. Treasury cash trading, Federal Reserve research found principal trading firms dominant on electronic interdealer venues, while primary and other dealers remained dominant across the Treasury market overall.

Foreign exchange demonstrates why electronic does not mean exchange-traded. The 2025 BIS Triennial Survey found that 59% of FX trading was electronic in April 2025, but the market remained fragmented across direct and brokered channels. Voice execution remained important for large spot trades and bespoke derivatives.

Fixed income shows the opposite edge of the spectrum. Automation is well established in futures and liquid benchmark government bonds, but high-yield and less-liquid corporate bonds still depend more heavily on dealers, RFQs and relationships. The less interchangeable the instrument, the less complete the replacement of the human desk.

What Actually Fell?

The decline was concentrated in specific functions rather than in trading as a whole:

  • The floor scalper lost the physical information advantage. Electronic access replaced the exchange seat with connectivity and software.
  • The manual trader lost the latency contest. A person cannot repeatedly reprice, cancel and hedge across several venues at machine speed.
  • The traditional proprietary bank desk became more constrained. Regulation, capital requirements and risk limits reduced some forms of balance-sheet speculation, although market-making remained.
  • Voice dealing declined in standardised and liquid products. It survived where size, discretion, credit and custom terms justify negotiation.
  • The visible exchange stopped representing the entire liquidity pool. Internalisation, ATSs, dealer platforms and bilateral networks became part of the execution landscape.

The fastest and most repetitive parts of the traditional desk were easiest to automate. Judgement-intensive, relationship-intensive and balance-sheet-intensive functions were more resistant.

Did Algorithmic Market Making Improve the Market?

The evidence is mixed but not evenly balanced. Automation has generally reduced transaction costs, accelerated price adjustment and increased quoted liquidity in normal conditions. CFTC research using account-level futures data found that greater high-frequency participation was associated with improved traded spreads and lower price impact. It also found that aggressive directional trading used by high-frequency firms to reduce inventory could damage market quality.

This is the central trade-off. Electronic liquidity is fast and competitive, but it can also be conditional. A traditional dealer may use capital and customer relationships to hold risk through a disturbance. A voluntary electronic market maker can widen its quotes, reduce size or withdraw when volatility, adverse selection or inventory risk breaches its limits.

Therefore, a narrow spread in calm conditions should not be confused with guaranteed depth during stress. Modern markets may be highly liquid on average while becoming fragile at precisely the moment everybody wants to trade.

Why Swing Trading Survived Better Than Traditional Day Trading

Automation attacks the shortest horizon first. If the expected opportunity lasts milliseconds, infrastructure determines who can capture it. If it lasts several minutes, execution still matters enormously. If it develops over days or weeks, latency becomes a much smaller part of the result.

Swing traders remain exposed to institutional algorithms, but they are not normally competing for the same spread or the same queue position. Their potential edge must come from slower information: macroeconomic change, earnings, policy, supply and demand, positioning, capital flows, sentiment or a persistent trend.

Day trading has also survived, but its viable role has narrowed. A human day trader is unlikely to beat a professional market maker at continuous two-sided quotation. The remaining advantage is selectivity: choosing an instrument, session, setup and risk level, and then choosing not to trade when conditions are unsuitable.

This has encouraged a hybrid model in which the human controls context, direction and permission while software manages scanning, order placement, exits, risk limits and repetitive execution. The human does not attempt to become the matching engine; the machine does not need to own every strategic decision.

The Modern Hierarchy of Market Power

  1. At microsecond and millisecond horizons, infrastructure dominates. Exchanges, high-frequency market makers, principal trading firms and automated dealer systems set the pace.
  2. At intraday horizons, systems and humans overlap. Execution algorithms, systematic funds, bank desks, prop firms and selective discretionary traders compete around news, liquidity and session structure.
  3. At multi-day and multi-week horizons, interpretation becomes more important. Asset managers, hedge funds, macro traders and swing traders accept more time and event risk in pursuit of larger moves.
  4. In illiquid or bespoke instruments, relationships and balance sheets still matter. Human sales traders, dealers, structurers and institutional networks remain central.

The faster the strategy, the more it has become a technology and capital business. The less standardised the asset, the more the traditional desk survives.

Conclusion: Trading Did Not Die; Its Competitive Boundary Moved

The rise of electronic and high-frequency trading did not abolish day trading or swing trading. It removed much of the easy economic space that once existed between slow information, wide spreads and limited market access.

Traditional human desks no longer control every stage of price discovery. Public exchanges now interact with private liquidity pools, bank platforms, dealer networks and automated market makers. The same instrument may be priced publicly, executed privately, hedged on another venue and cleared somewhere else.

For the modern trader, the decisive question is no longer simply whether a market will rise or fall. It is also: Who forms the price, on which venue, over what time horizon, with what information and at what execution speed?

At the shortest horizons, the answer is increasingly the machine. At longer horizons and in less-standardised markets, human judgement, relationships and controlled risk remain very much alive.

Sources and Further Reading

  • Chicago Mercantile Exchange Holdings: 2006 Annual Report
  • CME Group: Understanding Futures Open Interest
  • U.S. Securities and Exchange Commission: Concept Release on Equity Market Structure
  • U.S. Securities and Exchange Commission: Regulation NMS Final Rule
  • U.S. Securities and Exchange Commission: 2026 Proposal on the Trade-Through Rule and Market Fragmentation
  • U.S. Securities and Exchange Commission: Alternative Trading System List
  • U.S. Commodity Futures Trading Commission: Automated Trading in Futures Markets
  • U.S. Commodity Futures Trading Commission: High-Frequency Trading and Market Quality
  • Federal Reserve: Principal Trading Firm Activity in Treasury Cash Markets
  • Federal Reserve: Final Rules to Implement the Volcker Rule
  • Bank for International Settlements: The FX Trade Execution Landscape Through the 2025 Triennial Survey
  • Bank for International Settlements: Electronic Trading in Fixed-Income Markets
  • CME Group: Twenty Years of CME Globex
  • New York Stock Exchange: History of the NYSE

Filed Under: Algo Futures Trader, automated futures trading, ninjatrader automated trading Tagged With: algorithmic trading, automated trading, CME Globex, day trading, electronic trading, futures trading, futures volume, high-frequency trading, institutional trading, market making, Market Structure, open interest, private trading venues, swing trading, trading desks

Fully Automated Algo Trading Prop Firm Accounts

July 12, 2026 by AFT

Fully Automated Algo Trading for Prop Firm Accounts: Reality Versus Hype

The dream is simple: activate a profitable trading robot, allow it to trade a prop-firm account unattended and collect regular payouts without emotion, discretion or ongoing work.

The reality is considerably more complicated. A fully automated trading system can be profitable over time and still be completely unsuitable for the restrictive drawdown rules, trailing-loss limits and operational conditions commonly associated with retail futures prop accounts.

What Is a Fully Automated Trading System?

A fully automated trading system normally makes every major trading decision according to its programmed rules:

  • When to enter the market.
  • Whether to trade long or short.
  • Which instrument to trade.
  • How many contracts to use.
  • Where to place the stop loss and profit target.
  • How to manage the position after entry.
  • When to exit the trade.
  • Whether to continue trading as market conditions change.

Once activated, the system follows its instructions until its internal rules tell it to stop or a human operator intervenes.

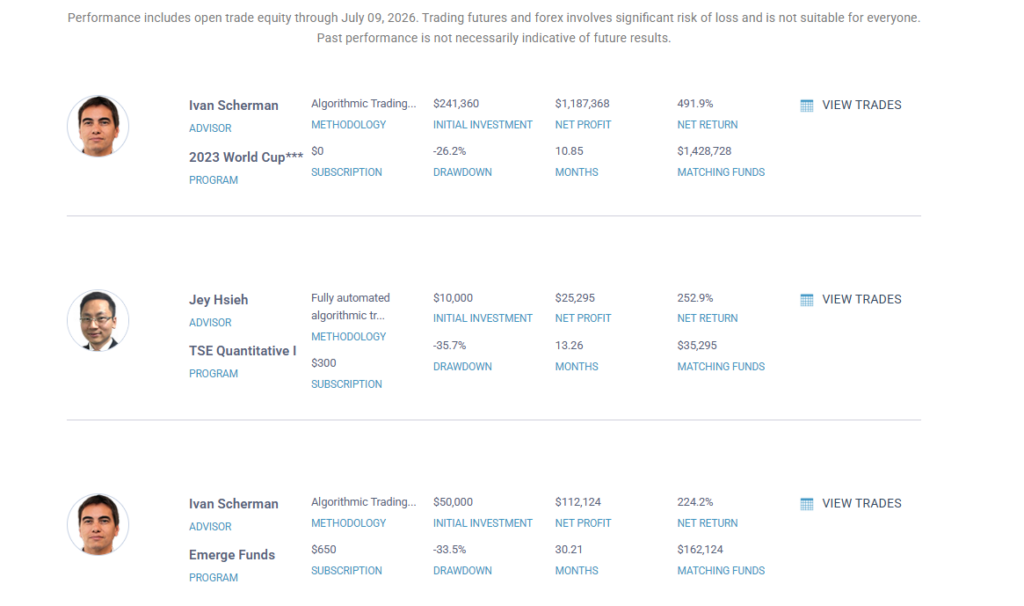
World Cup Advisor describes an AutoTrade service through which followers can select professional traders and have corresponding trades executed automatically in their accounts. It also states that its performance records include trade-by-trade histories and detailed performance reports.

A Trading Robot Is Usually Built Around a Specialized Edge

A credible automated system is not normally a magical machine that performs equally well in every market, instrument, trading session and volatility environment.

Most systems are designed around a particular trading premise, such as:

  • Trend following.
  • Mean reversion.
  • Momentum continuation.
  • Session breakouts.
  • Volatility expansion.
  • Statistical relationships between instruments.
  • Long-only or short-only market behavior.

When market conditions align with the system’s rules, the strategy may perform well. When those conditions disappear, the same system may enter a losing sequence or an extended drawdown.

The long-term premise is that profitable periods will eventually outweigh losing periods over the trader’s chosen measurement period, whether that is monthly, quarterly, annually or over several years.

However, the system must survive long enough to reach those profitable periods.

A Fully Automated System is a Blunt Instrument

A robot does not naturally understand that the market feels unusual, liquidity has deteriorated, correlations have broken down or an unexpected event has changed the trading environment unless those conditions have been anticipated and programmed into its logic.

It simply executes the rules it has been given.

This can make a fully automated system comparable to a blunt instrument. It may require substantial capital, sufficient margin, a large safety buffer and enough drawdown capacity to continue operating through unfavorable market phases.

A trader never knows whether a newly activated system will move immediately into profit or begin with its worst historical losing sequence.

The system may:

  • Enter drawdown immediately after activation.
  • Produce a strong profit before giving part of it back.
  • Remain stagnant for weeks or months.
  • Experience a market phase that was poorly represented in its historical testing.
  • Reach a new maximum drawdown before recovering.

One of the most common mistakes is stopping a system after accepting most of its losses, only to miss the profitable sequence that follows. Conversely, continuing to trade a deteriorating system indefinitely can create even greater losses.

Knowing the difference requires experience, research, monitoring and judgment. Fully automated trading does not remove the need for professional decision-making; it moves many of those decisions from individual trades to system selection, allocation, supervision and risk management.

Automation Does Not Remove Trading Psychology

Automation may reduce hesitation, impulsive entries, revenge trading and manual execution errors, but it does not eliminate psychology.

The emotional pressure simply changes form.

The operator must decide whether to:

  • Continue after several consecutive losses.
  • Reduce position size during a drawdown.
  • Pause the system when market conditions change.
  • Restart a previously paused strategy.
  • Accept that a system may have permanently lost its edge.
  • Trust a black-box model that the operator may not fully understand.

Many traders discover that they cannot remain committed to a system during a significant drawdown, particularly when they do not understand why the strategy is winning or losing.

Becoming proficient in fully automated trading can take months or years. The trader must find or create a model that fits the available capital, risk tolerance, operational infrastructure and personal psychology while accepting that the market phase supporting the system may eventually change.

The Mule Carrying Gold Up the Mountain

Imagine a mule carrying a sack of gold to a hut at the top of a mountain.

The mule must travel through forests, narrow paths, steep slopes, dead ends, falling rocks, snow, rain, wind and predators. It must reach the summit without losing its load or falling into a crevice from which it cannot recover.

Sending one mule along one path creates a concentrated risk of failure.

A professional operator might instead send several mules along different routes. Some may fail, some may be delayed and only a few may reach the summit. The successful journeys must produce enough value to outweigh the unsuccessful ones.

In systematic trading, this is known as diversification.

Rather than relying on one supposed “Holy Grail” robot that claims to work in all market conditions and across every instrument—an unrealistic and fundamentally flawed premise—professional automated portfolios may combine:

  • Multiple trading strategies.
  • Different instruments and markets.
  • Long-biased and short-biased models.
  • Trend-following and mean-reversion systems.
  • Different holding periods and timeframes.
  • Different volatility profiles.
  • Uncorrelated or less-correlated markets and strategies.

This approach requires deeper pockets, more sophisticated infrastructure, extensive research and significantly greater ongoing management than simply activating one robot on one small account.

The Advertised Prop-Account Size Is Not the Real Risk Capital

A nominal $50,000 prop account does not normally provide $50,000 of usable loss capacity.

The practical account size is determined by the permitted drawdown.

For example, a nominal $50,000 account with a $2,000 maximum-loss allowance gives the trader approximately 4% of the headline account value as total loss capacity.

The usable drawdown is the real account.

The effective allowance may be even smaller after accounting for:

  • Commissions and exchange fees.
  • Slippage.
  • Previous trading losses.
  • Daily-loss limits.
  • Trailing-drawdown movement.
  • Open-trade equity calculations.
  • The safety buffer required to prevent an accidental rule breach.

A robot designed for a normally capitalized brokerage account may therefore be completely unsuitable for a tightly constrained prop account.

What Published Automated-Trading Results Really Show

World Cup Advisor publishes performance information for selected professional traders and allows qualified subscribers to follow certain lead accounts automatically.

The following figures were recorded in the ATS source material after the market close on July 9, 2026:

World Cup Advisor fully automated trading statistics showing returns and published drawdowns

Examples of published automated and systematic trading results recorded on July 9, 2026.
Featured ProgramMethodologyNet ReturnPublished DrawdownPeriod
Ivan Scherman — 2023 World CupAlgorithmic trading491.9%26.2%10.85 months
Jey Hsieh — TSE Quantitative IFully automated algorithmic trading252.9%35.7%13.26 months
Ivan Scherman — Emerge FundsAlgorithmic trading224.2%33.5%30.21 months
Daniele Sambataro — Momentum SelectionSystematic trend following and mean reversion202.2%36.17%40.8 months

These are substantial published returns and should not be dismissed as poor trading, quite the opposite. The figures demonstrate that profitable professional systematic trading can still involve material drawdowns.

World Cup Advisor states that its published peak-to-valley drawdown represents the greatest cumulative percentage decline in month-end net equity during the life of the account. It also warns that followers may experience a larger percentage drawdown depending on their funding level, entry date, execution, and other factors.

The World Cup Trading Championships states that traders have participated in its events since 1983 and that competitors may use discretionary methods or computerized trading programs.

A profitable automated strategy can still be completely unsuitable for a tightly constrained prop account.

Performance figures are historical, may have changed since July 9, 2026 and should be independently verified before being relied upon for any trading decision.

Automated Drawdown Versus Prop-Account Drawdown

The published automated-system drawdowns in the examples range from approximately 26% to 36%.

By comparison, a hypothetical $50,000 prop account with a $2,000 maximum-loss allowance provides approximately 4% of the advertised account value as usable loss capacity.

Comparison with a hypothetical 4% maximum-loss allowance.
Published DrawdownCompared with a 4% Loss Limit
26.2%Approximately 6.6 times the allowance
35.7%Approximately 8.9 times the allowance
33.5%Approximately 8.4 times the allowance
36.17%Approximately 9 times the allowance

This does not mean the professional strategies are bad.

It means they were not necessarily designed for an environment in which a relatively small peak-to-trough movement can terminate the account.

To fit a strategy with a historical 30% drawdown inside a 4% maximum-loss allowance, the position size would normally have to be reduced substantially and an additional safety margin would still be required.

Reducing position size also reduces expected monetary returns. Trailing-drawdown mechanics may create additional path-dependent risk that cannot be solved by position sizing alone.

Return Without Drawdown Is Only Half the Story

Retail marketing frequently concentrates attention on:

  • Percentage returns.
  • Profit screenshots.
  • Winning months.
  • Smooth backtested equity curves.
  • High win rates.
  • Short prop-evaluation passes.

A percentage return has little meaning without understanding the risk, capital and time required to produce it.

A strategy producing a 100% return with a 35% drawdown might be acceptable to one properly capitalized investor and completely unusable for a prop trader with a 4% maximum-loss allowance.

The most important question is not:

“How much did the robot make?”

More useful questions include:

  • What maximum drawdown did the system experience?
  • How was the drawdown calculated?
  • Did it include real-time open equity or only closed trades?
  • How long did recovery take?
  • What happened during unfavorable market phases?
  • What was the longest losing sequence?
  • How much capital and margin were required?
  • Would the system survive the intended prop-firm rules?
  • How frequently must it be reviewed, paused or reoptimized?
  • Could the operator financially and psychologically continue trading it?

A strategy can eventually recover and still destroy a prop account long before that recovery occurs.

Why Trailing Drawdown Can Be Especially Dangerous

A trailing drawdown may move upward as the account reaches new equity highs.

Depending on the firm’s rules, the threshold may be calculated using the closed balance, end-of-day balance or intraday unrealized equity.

Under an intraday trailing model, a trade can move strongly into profit, raise the drawdown threshold, retrace and then fail the account even if the original trade would ultimately have closed profitably.

A robot designed around normal live-account fluctuations may therefore be unsuitable unless it has been developed and tested specifically around the exact drawdown mechanics of the intended account.

The system must not merely produce an eventual net profit. It must survive every step of the equity path required to reach that profit.

Prop-Firm Rules Can Restrict Professional Diversification

Professional systematic traders may reduce portfolio risk by combining multiple models, markets, parameter sets, timeframes and directional biases.

A prop firm may restrict or impose conditions on practices such as:

  • Fully unattended automated trading.
  • Account-copying technology.
  • Replicating identical trades across multiple accounts.
  • Holding opposing positions.
  • Hedging between related accounts or instruments.
  • Using different long-only and short-only models across allocations.
  • Trading during specified news events.
  • Holding positions outside permitted sessions.
  • Using third-party signals or shared systems.

These restrictions can prevent an automated trader from using the diversification normally required to operate a robust systematic portfolio.

The trader may instead be forced to run one concentrated strategy inside a very small drawdown allowance.

Rules vary between firms, account types, and trading platforms, and they may change. Traders must verify the current policy before using automation, multiple accounts, hedging, opposing positions, trade copiers, or third-party technology.

What Fully Automated Prop Trading Would Require

A trader considering fully automated trading on prop accounts should realistically expect to need:

  • A prop firm that expressly permits the intended form of automation.
  • A system developed around the firm’s exact drawdown rules.
  • Position sizing small enough to accommodate historical and unseen drawdowns.
  • A substantial safety buffer above the official loss threshold.
  • Accurate modeling of commissions, slippage, and rejected orders.
  • Controls for internet, platform, data-feed, and server failures.
  • Emergency shutdown and daily-loss controls.
  • Continuous performance monitoring.
  • A process for pausing, reviewing, and restarting systems.
  • Potentially several complementary systems rather than one robot.
  • Enough capital to tolerate failed evaluations and account resets.
  • Extensive forward testing under realistic execution conditions.
  • Extensive effort and time, monitoring, and hours spent on R&D

The strategy would need to perform materially better on a risk-adjusted basis than many professionally operated systems while remaining inside a much smaller drawdown envelope.

That is an exceptionally demanding objective.

Why the Failure Risk Can Be Extremely High

A generic automated strategy placed onto a typical, tightly constrained prop account without specific adaptation faces a high probability of breaching the account rules.

The risk increases when:

  • The strategy has not been designed for the account’s drawdown calculation.
  • The trader relies on one robot and one market.
  • The historical drawdown is close to the account’s entire loss allowance.
  • The system begins with a losing sequence.
  • The trader uses excessive contract size to pursue rapid payouts.
  • The system trades through unsuitable volatility or news conditions.
  • The operator cannot intervene when execution or technology fails.
  • The trader repeatedly stops systems after losses and restarts them after profits.

It would be misleading to assign a universal percentage to the probability of failure because the result depends on the strategy, position sizing, prop-firm rules and market conditions.

However, when an automated strategy with double-digit drawdown expectations is forced into an account offering only a small single-digit loss allowance, the structural risk of failure can become extremely high.

Why ATS Prefers Hybrid Algo Trading for Prop Accounts

ATS does not believe that automation is bad. ATS develops and uses algorithmic trading technology extensively.

The distinction is between using automation as a professional tool and expecting one unattended robot to replace the trader completely.

Hybrid algo trading combines:

  • Algorithmic market analysis.
  • Automated or assisted entries.
  • Automated trade management.
  • AI-supported market context.
  • Human control over risk and participation.
  • The ability to pause, reduce or adapt when conditions change.

This man-and-machine approach allows the trader to benefit from speed, consistency and structured execution while retaining control over conditions that are difficult to model reliably.

For tightly constrained prop accounts, the ability to decline a trade, reduce exposure, stop for the session or intervene during abnormal conditions can be more valuable than attempting to automate every decision.

Conclusion

  • Fully automated algo trading is not a shortcut to effortless prop-firm payouts, regardless of the hype promoted online or within trading groups.
  • A robot may perform well for a period without breaching the account rules, but every trading system will eventually experience losing trades, unfavorable market phases and drawdowns.
  • Credible automated trading generally requires significant research, suitable capital, sufficient drawdown capacity, ongoing monitoring, diversification and a professional operating process. These requirements can be extremely difficult to accommodate within a prop account offering only a 2% to 5% effective drawdown allowance.
  • A system can be profitable over the long term and still fail a prop account during an ordinary losing sequence. The central question is not whether the robot eventually makes money, but whether it can survive the restrictive path between activation and that eventual profit.
  • A retail trader must realistically ask whether they can produce better risk-adjusted results than experienced systematic traders while operating within substantially tighter drawdown constraints. For most traders, the answer is likely to be no.
  • An ATS robot could potentially be operated successfully by a highly skilled, properly capitalized trader within a suitable brokerage environment, particularly when the operator understands the system and uses the hybrid controls. That does not mean the same system can reliably survive the restrictive rules of a typical retail prop account.
  • When fully automated trading is permitted, the risk of an eventual rule breach can remain extremely high unless the system, position sizing, account structure and operating process have been designed specifically for that prop-firm environment.
  • Developing such a system would require extensive experimentation, testing, monitoring, time and ongoing refinement. ATS does not provide an off-the-shelf, ready-to-trade robot that can be expected to operate indefinitely within such restrictive drawdown rules.
  • A robot may experience a profitable run before eventually breaching the account rules, but that does not make the approach reliable or sustainable. When the drawdown allowance is extremely small, the long-term probability of failure can become unacceptably high.
  • These limitations explain why ATS uses a more practical hybrid trading system and methodology rather than promoting fully unattended automation as a dependable solution for prop-firm accounts.

A prop account does not give the robot room to be eventually right. It must remain within the rules at every stage of the journey.

What Is a More Viable Trading Solution for a Prop-Firm Account?

For many retail futures traders, a structured hybrid approach offers a more realistic pathway by combining automation, AI intelligence and human risk control instead of relying on a single unattended black-box system.

Book a Free ATS Discovery Meeting

Further Reading

  • Automated Futures Trading: What Retail Traders Need to Know
  • Dispelling Prop-Trading Myths and Misleading Funded-Account Claims
  • The Holy Grail Automated Trading Robot Versus How Automated Futures Trading Is Done Professionally
Risk Disclosure: Futures and prop-firm trading involve a significant risk of loss and are not suitable for every trader. Automated and hybrid systems can lose money. Past performance, hypothetical results and published third-party results do not guarantee future performance. Prop-firm rules, fees and account conditions vary and should be independently verified before trading. World Cup Advisor states that futures trading involves significant risk, that past performance is not necessarily indicative of future results and that there are no guarantees of profit.

Filed Under: AFT8, automated futures trading, prop firm trading Tagged With: algo trading, algorithmic trading, automated futures trading, Automated Trading Risk, Black Box Trading, Fully Automated Trading, futures prop firms, Futures Trading Systems, hybrid algo trading, man and machine trading, Prop Firm Drawdown, prop firm trading, Prop Trading Rules, risk management, systematic trading, Trading Algorithms, trading automation, Trading Robots, Trading System Drawdown, Trailing Drawdown

The Holy Grail Automated Trading Robot vs. How Automated Futures Trading Is Done Professionally

July 11, 2026 by AFT

The retail trading dream is one automated robot that trades every market, survives every condition, produces consistent profits and requires no further involvement. Switch it on, go and play golf and retire forever. Professional automated trading looks very different.

The Automated Trading Dream

Many traders search for a single automated trading robot with an impressive win rate, an attractive risk-to-reward ratio and a smooth historical equity curve. They want one set of settings that can trade long and short, operate on any futures instrument, work throughout every market phase and continue indefinitely without intervention.

The assumption is that once this robot has been discovered, the difficult work is finished. The trader can switch it on, leave it unattended and watch the profits accumulate.

This is the retail trading version of the “holy grail.” It is also one of the most persistent myths surrounding fully automated trading.

Why One Robot Cannot Excel in Every Market Condition

Futures markets continually move between different conditions, including trends, ranges, high volatility, low volatility, expanding volume, contracting volume, news-driven movement and irregular price behaviour. A strategy designed to exploit one condition can perform poorly when the market changes into another.

A trend-following robot can struggle in a sideways market. A mean-reversion robot can be damaged by a powerful breakout. A long-biased strategy may perform well during a sustained bullish phase but become unsuitable when the wider structure turns bearish. A strategy calibrated for quiet overnight trading may behave very differently during the volatile New York open.

The more conditions one robot attempts to cover, the more compromises are usually introduced. It can become a blunt instrument that is average at many tasks but excellent at none.

How Automated Trading Is Done Professionally

Professional automation is normally approached as a portfolio of specialised systems rather than one universal robot. Each system is designed for a defined task, market, direction, session or market condition in which it has demonstrated an identifiable advantage.

  • Specialised strategies: A robot is created to perform a specific task that it can execute consistently rather than being expected to trade everything.
  • Defined instruments: A system may be developed specifically for an equity index, energy, metal, currency, agricultural or interest-rate futures market.
  • Defined directions: Some systems may trade long only, short only or both directions according to the market phase.
  • Defined sessions: A strategy may operate only during selected periods, such as the European session, New York open, regular trading hours or overnight market.
  • Controlled activation: Systems may be switched on, reduced, paused or parked when conditions become unsuitable or predefined drawdown limits are reached.
  • Portfolio construction: Capital is distributed across different systems and preferably less-correlated instruments, behaviours and return streams.
  • Continuous supervision: Performance, execution quality, slippage, risk limits, infrastructure and market behaviour remain under observation.
  • Ongoing research: Systems are repeatedly tested, reviewed and adjusted as markets, volatility, liquidity and participant behaviour change.

The Holy Grail Robot vs. Professional Automated Trading

The Holy Grail MythProfessional Reality
One robot trades everything.Multiple specialised systems perform clearly defined tasks.
One set of parameters works forever.Parameters and system suitability must be monitored as market behaviour changes.
The robot trades continuously.Systems can be activated, restricted, reduced, paused or parked.
The robot always trades long and short.Some strategies operate long only, short only or only during selected market phases.
Automation removes the need for risk management.Professional automation depends on strict position, order, account and portfolio-level controls.
A strong backtest is sufficient.Development normally includes backtesting, replay, simulation, forward testing, pre-production and carefully controlled live deployment.
Automation means less work.Reliable full automation requires substantial development, infrastructure, monitoring and ongoing research.
A small account can run many systems.Each system requires sufficient risk allocation, margin capacity and drawdown tolerance.

The Real Holy Grail Is Diversification, Not One Robot

Ray Dalio describes his investment “holy grail” as striving to hold “15 good uncorrelated investments that are risk balanced.” His principle is not to find one perfect investment or prediction, but to combine multiple quality return streams so that the portfolio is not dependent on one concentrated bet.

The same principle can be applied conceptually to automated trading. Instead of searching for one robot that must always be correct, the professional objective is to build a collection of specialised systems whose risks, market dependencies and periods of strength are not identical.

Owning five robots does not automatically create diversification. Five strategies trading similar logic on ES, NQ and other closely related equity-index futures may all lose together. Genuine diversification requires attention to instrument correlation, strategy logic, timeframe, market regime, trade direction and the underlying source of each system’s returns.

Professional Automation Requires Controls and Infrastructure

Professional automation is not simply a trading strategy connected to a brokerage account. It is an operating environment containing development controls, risk controls, monitoring, records, recovery procedures and human responsibility.

National Futures Association guidance for automated order-routing systems addresses security, capacity, stress testing, pre-execution limits, post-execution monitoring, alerts, contingency planning and redundant systems. This illustrates how seriously automated execution must be treated when real orders and financial exposure are involved.

A more complete automated trading operation may require historical tick data, backtesting and replay environments, simulation accounts, forward-testing servers, pre-production systems, live-production systems, monitoring, alerts, logs, backup connectivity and procedures for immediately disabling a malfunctioning strategy.

The robot may place the trade, but people remain responsible for the system, its behaviour and the financial consequences.

Be Prepared for Significant Capital Requirements

There is no universal account size that makes fully automated trading safe or viable. Capital requirements depend on the futures contracts being traded, volatility, contract size, margin, strategy frequency, expected drawdown, number of systems and the amount of correlation between them.

CME Group explains that futures risk should be managed through the contract selected, the number of contracts traded and stops aligned with the trader’s risk tolerance. It also warns traders to size positions according to realistic risk scenarios rather than simply trading the maximum quantity allowed by broker margin.

A professional automated portfolio needs sufficient capital to allocate risk across several strategies while allowing each strategy to survive normal losing periods. Attempting to place numerous automated systems inside one small account with a tight maximum-loss or trailing-drawdown rule can create a structural mismatch between the portfolio design and the available risk budget.

Micro futures can improve position-sizing flexibility, but they do not remove market risk, strategy risk, correlation risk, slippage, technical failures or drawdown.

Be Prepared for Months or Years of Work

Fully automated trading is frequently marketed as a way to save time. Building it properly can require considerably more time than learning to trade one structured hybrid methodology.

At ATS, we regard six to twelve months as a strong start for serious automated system development. A professional multi-system operation can take one to three years to research, develop, test, forward test and prepare for carefully controlled live deployment.

The work does not finish when a system reaches the market. Strategies must continue to be reviewed because liquidity, volatility, correlations, contract behaviour and market participants change. A successful strategy may later need to be reduced, modified, transferred to another instrument or parked until its preferred conditions return.

Professional automation is an ongoing research and risk-management operation, not a one-time software installation.

The Hybrid Algo Trading Alternative

Most individual futures and prop-firm traders do not have the capital, infrastructure, technical resources or development timeline required to build a professionally diversified fully automated operation.

Hybrid algo trading provides a more practical route by combining human market awareness with algorithmic execution, structured risk management and real-time decision-support technology.

The trader remains responsible for deciding whether the market conditions, direction, timing and risk are suitable. The technology assists with identifying opportunities, executing repeatable processes, managing orders and reducing emotional interference.

This man-and-machine approach allows the algorithm to perform the tasks at which software excels while the trader retains control over the areas where changing context, judgement and adaptability remain important.

The ATS Hybrid Algo Futures Trading Solution

ATS is designed to provide a faster and more accessible route to market for serious futures and prop-firm traders, including traders working with smaller accounts and micro futures on suitable $25K prop-account programmes.

  • Algo Futures Trader: Provides semi-automated and automated trading tools, structured entries, trade management, exits and real-time control.
  • Alpha Web Trader: Provides market context, confirmation, correlations, trend information and decision-support intelligence.
  • AI Trading Copilot: Assists with market preparation, risk, news, context, setups and live-session awareness.
  • Turnkey workspaces: Give traders structured starting points for learning, testing and developing their own repeatable process.
  • ATS Trader Fast Track: Provides assisted onboarding, platform setup, hybrid methodology, workspace guidance, trade planning and a structured pathway towards prop or live-trading readiness.
  • VIP Trading Group: Provides live-market education, instruction, context and continuing development within the ATS trading framework.

ATS baseline algorithms are reference starting points for understanding market phases, testing ideas and learning how systems win and lose. They are not presented as universal set-and-forget robots or guaranteed live-trading solutions.

The objective is to help traders pursue maximum profit, minimum drawdown and least emotion through a controlled hybrid process. These are trading goals, not promises or guarantees.

Which Path Is Right for You?

Fully automated trading may suit experienced, technically capable and well-capitalised traders who are prepared to commit to extensive research, infrastructure, portfolio construction and ongoing system management.

Hybrid algo trading may provide a more realistic route for traders who want to reach the futures or prop-firm market sooner, retain direct control and use automation without depending on an imaginary robot that must work in every market condition forever.

The most important decision is not which robot has the most attractive historical statistics. It is whether your chosen approach is compatible with your capital, available time, technical ability, risk tolerance and long-term commitment.

Discuss Your ATS Trading Pathway

Book a free, obligation-free ATS Discovery Meeting to discuss your current experience, trading goals, available time, account plans and whether the self-assisted, Fast Track or longer-term automated development route is the most suitable fit.

🎧 Book Your Free ATS Discovery Meeting

Sources and Further Reading

  1. Ray Dalio: Investment Principles — What Should You Do Under Existing Conditions?
  2. National Futures Association: Supervision of the Use of Automated Order-Routing Systems
  3. CME Group: Position and Risk Management for Futures Traders

Risk Disclosure: Futures and prop-firm trading involve a significant risk of loss and are not suitable for every trader. Automated, algorithmic and hybrid trading systems can lose money and may experience slippage, technical failures, changing market behaviour and extended drawdowns. Historical, hypothetical, simulated or baseline results do not guarantee future performance. Prop-firm rules, account conditions and permitted automation vary by provider and can change. Traders must review and comply with all applicable rules before using any automated or semi-automated technology.

Filed Under: AFT8, automated futures trading, fully automated trading system, NinjaTrader 8, ninjatrader automated trading Tagged With: algo futures trader, algorithmic trading, ATS Trader Fast Track, automated futures trading, automated trading, Fully Automated Trading, futures trading, hybrid algo trading, Micro Futures, professional trading systems, prop firm trading, Trading Risk Management, Trading Robots, trading system diversification, uncorrelated strategies

Why ATS Does Not Recommend Fully Unattended Automated Trading for Prop Firms

July 8, 2026 by AFT

ATS purpose-built prop-trading toolsets combine trader judgement, algorithmic execution and AI-assisted market intelligence to pursue maximum profit potential, minimum drawdown and the least possible emotional interference.

These are trading objectives, not promises or guarantees. Futures and prop-firm trading involve a significant risk of loss.

The Fully Automated Prop-Trading Dream

Many traders come to ATS searching for a completely automated futures-trading system after struggling with hesitation, overtrading, revenge trading, fear, greed or inconsistent execution.

The proposed solution sounds compelling: switch on a robot, allow it to trade without emotion and let it pass prop evaluations, protect funded accounts and generate payouts without continuous trader involvement.

Some traders want one algorithm with a high win rate, an attractive risk-to-reward ratio, low drawdown and the ability to trade every market condition indefinitely. They expect the same settings to operate through trends, ranges, high volatility, low volatility, economic news, holidays and changing liquidity without requiring supervision or adjustment.

The problem is not that automated trading is impossible. Professionally developed automated systems can be effective when they are properly researched, tested, diversified, capitalized, monitored and maintained.

The problem is expecting one fixed retail trading robot to perform every task, survive every market phase and remain safely inside a tightly constrained prop-account drawdown without active oversight.

There is a major difference between an algorithm that can produce attractive historical statistics and an automated trading operation that can survive changing markets, live execution and restrictive prop-firm rules.

The Advertised Prop-Account Size Is Not the Real Risk Capital

A nominal $50,000 prop account does not normally give the trader or algorithm $50,000 of capital that can be lost.

The practical risk budget is the account’s permitted drawdown.

For example, a $50,000 account with a $2,000 maximum-loss allowance provides approximately 4% of its headline account size as total loss capacity. A $250,000 account with a $5,000 loss allowance provides only approximately 2% of its advertised value as usable loss capacity.

The effective allowance may be smaller after commissions, slippage, previous losses, daily-loss rules, trailing-drawdown movement and the safety buffer required to prevent an accidental account failure.

The real account is not the number printed in the account name. The real account is the drawdown allowance that the strategy must survive.

A profitable automated strategy may eventually recover from a significant losing period when operated inside a sufficiently capitalized brokerage account. The same strategy could fail a prop account long before its statistical advantage has enough time to recover.

In prop trading, profitability over a large sample is not enough. The system must survive every stage between account activation and a permitted payout.

Prop Trading Combines Market Risk With Account-Rule Risk

A prop-trading algorithm must do more than identify potentially profitable trades. It must also operate within the exact rules of the selected firm and account programme.

Depending on the provider and account type, these rules may include:

  • Daily-loss limits.
  • Intraday or end-of-day trailing drawdown.
  • Maximum position sizes.
  • Scaling requirements.
  • Consistency rules.
  • Minimum trading days.
  • News-trading restrictions.
  • Holding-time restrictions.
  • Payout buffers and withdrawal requirements.
  • Restrictions affecting automated trading, account access or trade copying.

Rules vary between firms and programmes and may change. Traders remain responsible for verifying and complying with the current terms of every account they trade.

An algorithm can identify a technically valid trade that fits its historical statistics while the trade remains inappropriate for the prop account because the remaining drawdown cannot support the risk.

A human risk controller can reject that trade, reduce its size, stop trading for the day or wait for a higher-quality opportunity. A fully unattended robot will continue unless that precise account condition has already been programmed, tested and correctly synchronized with the firm’s current rules.

Markets Change, but Fixed Rules Do Not Think

Futures markets continually move through trends, ranges, volatility expansion, volatility contraction, changing correlations, liquidity shifts, irregular price behaviour and news-driven movement.

A trend-following system can struggle when the market becomes rotational. A mean-reversion system can suffer when a sustained breakout develops. A strategy calibrated for quiet overnight trading may behave very differently during the New York open.

When market conditions change, a professional system operator may need to:

  • Pause or park the system.
  • Reduce position size.
  • Restrict trading to a selected session.
  • Permit long trades only or short trades only.
  • Apply volatility, liquidity or market-structure filters.
  • Switch to a different strategy or instrument.
  • Reoptimize and forward-test updated settings.
  • Retire the system if its original advantage no longer appears valid.

The belief that one algorithm should trade continuously through every condition is not professional diversification. It is dependence on one fixed collection of assumptions.

This is especially dangerous when the account can be terminated by a relatively small peak-to-trough decline.

What Published Automated-Trading Results Really Show

World Cup Advisor publishes performance information from experienced futures and forex traders and offers an automatic leader-follower service through which selected trades can be replicated in subscriber accounts. The organization states that the World Cup Trading Championships has attracted leading traders since 1983. :contentReference[oaicite:0]{index=0}

The ATS screenshot reproduced below records figures displayed after the market close on July 9, 2026:

World Cup Advisor automated trading statistics showing published returns and drawdowns
Examples of automated and systematic trading results published by World Cup Advisor and captured by ATS after the market close on July 9, 2026.
Examples of published automated and systematic trading results.
Featured ProgramMethodologyNet ReturnPublished DrawdownPeriod
Ivan Scherman — 2023 World CupAlgorithmic trading491.9%26.2%10.85 months
Jey Hsieh — TSE Quantitative IFully automated algorithmic trading252.9%35.7%13.26 months
Ivan Scherman — Emerge FundsAlgorithmic trading224.2%33.5%30.21 months
Daniele Sambataro — Momentum SelectionSystematic trend-following and mean reversion202.2%36.17%40.8 months

These are substantial published returns and should not be dismissed as poor trading. The results do not suggest that the advisors are unskilled. They demonstrate what experienced traders and professionally operated systematic programmes may achieve when supported by research, capital, infrastructure and risk tolerance.

However, the drawdowns reveal an equally important part of the performance profile.

A profitable automated strategy can still be completely unsuitable for a tightly constrained prop account.

World Cup Advisor explains that its published peak-to-valley drawdown is based on the greatest cumulative percentage decline in month-end net equity and warns that subscribers can experience a greater percentage drawdown depending on their funding level. It also states that subscriber performance may differ because of execution, slippage, funding and other factors. :contentReference[oaicite:1]{index=1}

Source: World Cup Advisor. The figures above were captured on July 9, 2026, may subsequently change and should be independently verified.

Automated Drawdown Versus Prop-Account Drawdown

The listed automated-system drawdowns range from approximately 26% to 36%.

By comparison, a nominal $50,000 futures prop account with a $2,000 maximum-loss allowance provides approximately 4% of the advertised account size as loss capacity.

Published strategy drawdowns compared with an illustrative 4% prop-account loss allowance.
Published DrawdownCompared With a 4% Loss Limit
26.2%Approximately 6.6 times the limit
35.7%Approximately 8.9 times the limit
33.5%Approximately 8.4 times the limit
36.17%Approximately 9 times the limit

This does not mean that the published strategies are bad or unprofitable.

It means they were not necessarily designed for an account environment in which a relatively small peak-to-trough movement can terminate the trading programme.

Attempting to place a strategy with a historically larger drawdown inside a 4% loss allowance would normally require a substantial reduction in position size. That reduction would also reduce the expected monetary returns, while trailing-drawdown mechanics, commissions, slippage and the sequence of wins and losses could still create additional risk.

A strategy can therefore be profitable over its complete performance history and remain structurally unsuitable for a specific prop account.

The Robot Must Survive the Path to Profitability

Consider a strategy with positive long-term expectancy that risks $250 per trade.

Four consecutive losses would produce approximately $1,000 of trading loss before commissions and slippage. On a nominal $50,000 prop account with a $2,000 maximum drawdown, that sequence could consume approximately half of the entire loss allowance.

A further losing sequence, execution error or volatile trade could terminate the account even though the strategy remains profitable over a much larger statistical sample.

The robot may eventually recover statistically. The failed prop account cannot wait for that recovery.

This is why win rate, net profit and risk-to-reward ratio are not enough to determine whether an automated strategy is suitable for prop trading.

A serious assessment should also consider maximum drawdown, losing-run length, adverse excursion, trade clustering, slippage, commissions, market-regime dependence, parameter sensitivity, open-trade equity movement and compatibility with the account’s current rules.

Fully Automated Trading Does Not Remove the Work

Retail automated trading is often marketed as a way to avoid the effort involved in trading. Professional automation normally transfers the workload from individual trade execution into system development and operation.

A serious automated trader may need to act as:

  • A strategy developer.
  • A quantitative researcher.
  • A software tester.
  • A data and infrastructure operator.
  • A portfolio manager.
  • A real-time risk supervisor.

The work can include historical testing, out-of-sample testing, replay, simulation, forward validation, realistic commissions and slippage, drawdown controls, shutdown procedures, system monitoring, data management, backup connectivity and ongoing revalidation as markets change.

ATS regards approximately six to twelve months as a strong start for developing and cautiously introducing an initial automated system. Building a diversified operation containing multiple systems and return streams may require one to three years or longer, with no guarantee that the total investment will become profitable. :contentReference[oaicite:2]{index=2}

Professional automation is not a one-time software installation. It is an ongoing research, engineering and risk-management operation.

How Fully Automated Trading Is Done Professionally

Professional automated trading is normally built around a portfolio of specialized systems rather than one universal robot.

Each system may be designed for a defined instrument, market condition, session, direction or trading task in which it has demonstrated a measurable advantage.

  • Specialized strategies: Each system performs a clearly defined task rather than attempting to trade every condition.
  • Defined instruments: Systems may be developed for selected equity-index, energy, metal, currency, agricultural or interest-rate futures markets.
  • Defined directions: Some systems may trade long only, short only or both directions according to the market phase.
  • Defined sessions: A strategy may operate only during the European session, New York open, regular trading hours or overnight market.
  • Controlled activation: Systems may be activated, restricted, reduced, paused or parked according to market conditions and predefined risk limits.
  • Portfolio construction: Capital may be distributed across multiple systems and preferably less-correlated instruments, behaviours and return streams.
  • Continuous supervision: Risk, execution, connectivity, slippage, system health and market behaviour remain monitored.
  • Ongoing research: Strategies are reviewed and revalidated as volatility, liquidity, correlations and participant behaviour change.

The machine may place the trades, but people remain responsible for the systems, the risk controls and the financial consequences. :contentReference[oaicite:3]{index=3}

The ATS Alternative: Hybrid Algo Trading

ATS is not built around replacing the trader with a black-box robot.

ATS is built around a Hybrid Man + Machine trading framework in which technology performs the tasks that software handles exceptionally well while the trader remains responsible for the decisions requiring context, adaptability and accountability.

The objective is not merely to automate more trades.

The objective is to improve trade selection, strengthen execution, reduce emotional interference, manage risk and help the trader operate through a structured professional process.

Division of responsibility within the ATS Hybrid Algo Trading framework.
The Machine SupportsThe Trader Controls
Rapid calculations and continuous technical monitoringWider market context and session suitability
Rule-based opportunity identificationTrade approval and opportunity selection
Structured order placementAccount-level risk authorization
Automated stops, targets and trade managementPosition size, scaling and remaining drawdown
Consistent execution without hesitationNews, liquidity and abnormal-market awareness
Alerts, data and market intelligenceThe decision to pause, reduce risk or stand aside

This is not random emotional intervention. Professional hybrid control applies predefined higher-level decisions intended to protect the account when an immediate algorithmic signal does not represent the complete trading environment.

Hybrid trading retains the speed, structure and discipline of automation without surrendering control of the account completely. :contentReference[oaicite:4]{index=4}

The objective is not to become a passenger watching a robot trade. The objective is to become a better pilot.

The ATS Hybrid Algo Futures Trading Ecosystem

ATS combines trading technology, market intelligence, AI-assisted decision support, structured workspaces, trader education and continuing development within one purpose-built futures and prop-trading environment.

AFT — Algo Futures Trader

AFT is the NinjaTrader-based execution and automation platform at the centre of the ATS ecosystem. It supports rule-based opportunity identification, assisted entries, configurable automation, structured execution, automated trade management and direct real-time trader control.

AWT — Alpha Web Trader

AWT provides an additional market-intelligence and confirmation layer, including direction, trend state, volatility, structure, correlations and higher-probability trading context.

AI Trading Copilot

The AI Trading Copilot supports session preparation and live-market decision-making with information covering risk, economic news, earnings, holidays, market conditions, correlations, setups and trading-plan context.

Turnkey Trading Workspaces

ATS turnkey workspaces provide structured starting points for learning, testing and trading selected futures and prop-account methodologies. Baseline algorithms are reference tools for understanding how systems behave through winning, losing and changing market phases; they are not presented as universal set-and-forget live-trading robots.

VIP Trading Group

The VIP Trading Group provides a focused environment for live-market education, trading context, market intelligence, structured discussion and continuing development within the ATS methodology.

ATS Trader Fast Track and Mastery

ATS Trader Fast Track and Mastery help traders install and configure the technology, understand the Hybrid Algo Trading Methodology, build a trade plan, establish risk controls, practise correctly and develop their own statistics through review and repetition.

Maximum Profit Potential. Minimum Drawdown. Least Emotion.

These are the operating objectives behind the ATS Hybrid Algo Trading Methodology.

They are not guaranteed outcomes, and no trading technology can eliminate losses, drawdown, execution risk or human responsibility.

ATS can provide the technology, framework, workspaces, market intelligence, education, support and development pathway.

The trader must still practise, follow the process, control risk, maintain statistics, review mistakes, remain disciplined and trade only when the market and account conditions justify participation.

Technology can make a committed trader more capable. It cannot make an uncommitted trader successful.

For many serious futures and prop-firm traders, this controlled and adaptable approach is more practical than spending months or years attempting to build a fully autonomous quantitative trading operation.

The ATS Solution: Hybrid Algo Trading for Prop Firms

ATS provides a practical Man + Machine trading pathway for traders who want the advantages of automation while retaining control of market selection, trade approval, account risk and the decision to stand aside.

Rather than handing the account to one fixed robot and hoping that its historical assumptions remain valid, the ATS trader can use AFT, AWT, AI Copilot, turnkey workspaces, VIP market intelligence and Mastery support as one coordinated trading process.

The machine provides speed, structure, calculations, monitoring and execution support.

The trader provides judgement, accountability, adaptability and final risk control.

Book a free, obligation-free ATS Discovery Meeting to discuss your experience, trading goals, available time, prop-firm or brokerage plans and whether the ATS Hybrid Algo Trading pathway is the right fit.

🎧 Book Your Free ATS Discovery Meeting

ATS Further Reading

  • The Holy Grail Automated Trading Robot vs. How Automated Futures Trading Is Done Professionally
  • Just Give Me an Algo That Works
  • Hybrid Algo Trading Versus Fully Automated Trading: The Time and Effort Required
  • Why We Love Hybrid Algo Trading for Prop-Firm and Live Brokerage Account Trading
  • World Cup Advisor Published Trading Programmes and Performance Information

Important Risk Disclosure

Futures, leveraged and prop-firm trading involve a significant risk of loss and are not suitable for every trader. Automated, algorithmic and hybrid trading systems can lose money and may experience changing market behaviour, slippage, technical failures, execution differences and extended drawdowns.

Past, hypothetical, simulated, baseline or published performance does not guarantee future results. Performance statistics, account examples, drawdown comparisons and development timelines in this article are provided for educational and illustrative purposes only and are not earnings claims, promises, investment advice or guarantees.

Prop-firm rules, account conditions, drawdown calculations, fees, automation policies and payout requirements vary and may change. Traders must independently verify and comply with the current rules of every prop firm, brokerage, platform and account they use.

Filed Under: AFT8, automated futures trading, ninjatrader automated trading, prop firm trading Tagged With: AI Copilot, algo futures trader, Alpha Web Trader, ATS Mastery, Hybrid Trading, prop firm trading, Semi Automated Trading

ATS Futures Trading Group Rebooted!

May 21, 2026 by AFT

ats vip trading group

VIP Trading Group Rebooted and Expanded so you got it all in 1 place, all you need for day trading prop trading

The VIP Trading Group has been rebooted and reorganized to create a cleaner, more focused environment for live market trading. The goal is to bring together live market flow, trader education, AI-assisted insights, technical analysis, trade signals, statistics, and market news in one place for active futures traders.

  • Signup and Link Your Account
  • Get VIP Elite Access
  • VIP Trading Groups

⚡ Trading Zone

Enhanced trade mastery, AI-assisted trader education, and market information are shared in a live trading environment focused on U.S. indices prop and day trading, typically from 8:15 AM CT to 11:00 AM CT, Monday through Friday.

  • The VIP Trade Chat section has moved from the ATS Support & Education Group into the VIP Trading Group, creating a dedicated live market trading environment for VIP traders.
  • Trading Zone hours: Monday to Friday, 8:15 AM CT to 11:00 AM CT is the primary live market session.
  • AI Trade Copilot commentary, pre-session analysis, and intraday market updates focused primarily on U.S. indices.
  • VIP Elite members and trialists may have read-only access depending on membership level.
  • Trade Mastery education and information may be posted by approved traders who have earned the ATS Trade Coach badge through the Zero to Hero process.
  • The objective is straightforward: follow the trade plan, use proven turnkey workspaces, and apply hybrid trading methods for Maximum Profits, Minimum Drawdown, and Least Emotion.
  • Market focus includes S&P 500 (ES), Nasdaq (NQ), Mid Cap (EMD), Small Cap (RTY), and related micro futures contracts.

Trading Education and Information

Additional educational content, trading insights, and trader-development material may be contributed by veteran ATS founders, experienced traders, and approved members who have earned the ATS Trade Coach badge through the Zero to Hero progression.

Topics may include trade planning, market structure, trader psychology, hybrid trading workflows, risk management, platform usage, execution techniques, and practical lessons learned from evaluation, prop firm, and live trading environments.

📰 Market News

The market-news channel provides market-moving news context and catalysts for U.S. indices futures traders.

Content focuses on pre-session preparation and key updates throughout the trading day covering U.S. equities, Treasury markets, oil, gold, economic releases, earnings, Federal Reserve commentary, and major risk events that may influence market direction and volatility.

The objective is to help traders understand the news environment surrounding price action without needing to monitor multiple external news sources.

🌡️ Sentiment

The sentiment channel provides a market sentiment dashboard showing bullish, bearish, and neutral news sentiment across indices, ETFs, commodities, sectors, and major market themes.

Sentiment data is intended to provide additional market context and awareness. It should be used as informational context rather than as a standalone trading signal.

🎯 Trade Signals

The trade-signals channel delivers trade signals, technical alerts, and market opportunities generated from ATS Hybrid Algo Trading systems.

Instrument Focus:

  • Equity Indices: ES, NQ, EMD, RTY
  • Commodities: CL, GC
  • Crypto: BTC

Signal types include ATS Session Breakout and trend-following systems such as DSFG, DSFG Gap, WSFG, MSFG, TR120, and TR720. Traders should use signals as market context and signal flow within their own trade plans, risk management rules, and decision-making processes.

🏆 Trades-n-Stats

The trades-n-stats channel has moved into the VIP Group and is open to VIP Trialists and VIP Elite members.

This channel focuses on hybrid trading statistics from real trade plans — the good, the bad, and the ugly.

VIP Elite members have read/write access. The purpose is to learn how to win by following a process, not by chasing random methods or repeating losing habits.

🔴 Trade Streams

The trade-streams channel has been revamped to focus on ES, NQ, EMD, and RTY, providing a static live market view during real-time trading hours.

The stream provides real-time Algo Server chart views, typically running from Monday 7:00 AM CT through Friday market close. The Discord stream channel itself remains available 24/7.

The primary focus is the ATS Session Breakout flagship trade plan, showing live market algo trading directly on the charts with baseline entries and exits displayed for reference.

Content Lifecycle

To keep information fresh, relevant, and easy to consume in a live trading environment, most VIP Group channels automatically self-delete content daily.

Over weekends, the final trading day’s content remains visible until the next market open, allowing traders to review the most recent market context before the new trading week begins.

Summary

The VIP Trading Group is now structured to provide traders with a complete live market ecosystem that combines market news, sentiment analysis, trade signals, live trading discussion, education, statistics, and real-time chart streams in one focused environment. Whether trading evaluation accounts, prop firm accounts, or live capital, the goal remains the same: build consistency through process, discipline, and hybrid man-plus-machine trading.

Filed Under: AFT8, ATS Trading Community, automated futures trading, get funded trading, ninjatrader automated trading, prop firm trading Tagged With: Day Trading Futures Group, trade group

  • 1
  • 2
  • 3
  • …
  • 7
  • Next Page »
  • NinjaTrader Automated Trading
  • automated futures trading
  • automated trading systems
  • Day Trading Futures
  • Get Started Day Trading Futures
  • VIP Trading Group Live Market Trade Along
  • Secret to Day trading futures success
  • AFT8 for NinjaTrader 8
  • Futures Algo Trading Systems
  • Market News
  • NinjaTrader Free Trading Platform
  • Legal Notices
  • AFT Legal Info
  • Terms
  • FULL RISK DISCLOSURE
  • Privacy Policy
  • Cookie Usage
  • About AlgoFuturesTrader
  • Connect to AFT
  • Blog
  • Videos
  • Support
  • Contact
  • My account
  • Sitemap
  • Affiliates

Ninja Futures Trading
Algo Futures Trader Copyright Algo Trading Systems© 2026 ¡
AlgoFuturesTrader.com is owned & operated by Algo Trading Systems LLC. By using this website or products & services, you are bound by our Terms & subject to US legal jurisdiction only. Errors & omissions excluded.
AFT made in England, powered by MicroTrends NinjaTrader development

Disclaimer: Trading & investment carry a high level of risk. AlgoFuturesTrader does not make recommendations for buying or selling any financial instruments, nor do we offer trading or investment advice. We are a software company, and we only provide educational information on ways to use our sophisticated Algo Futures trading tools. It is up to our customers & readers to make their own trading & investment decisions, or consult with a registered investment advisor.

Risk Disclosure: Futures, CFDs, & forex trading carry substantial risk and are not suitable for every investor. An investor could potentially lose all or more than the initial investment. Risk capital is money that can be lost without jeopardizing one's financial security or lifestyle. Only risk capital should be used for trading, and only those with sufficient risk capital should consider trading. Past performance is not necessarily indicative of future results. Please read the full risk disclosure here.

Hypothetical performance results have many inherent limitations, some of which are described below. No representation is made that any account will or is likely to achieve profits or losses similar to those shown. In fact, there are frequently sharp differences between hypothetical performance results and the actual results subsequently achieved by any particular trading program. One of the limitations of hypothetical performance results is that they are generally prepared with the benefit of hindsight. In addition, hypothetical trading does not involve financial risk, and no hypothetical trading record can completely account for the impact of financial risk in actual trading. For example, the ability to withstand losses or adhere to a particular trading program despite trading losses are material points that can adversely affect actual trading results. Numerous other factors related to the markets or the implementation of any specific trading program cannot be fully accounted for in the preparation of hypothetical performance results and can adversely affect trading results.

Testimonials appearing on this website may not be representative of other clients or customers and are not a guarantee of future performance or success.

NinjaTraderÂŽ is a registered trademark of NinjaTrader Group, LLC. No NinjaTrader company has any affiliation with the owner, developer, or provider of the products or services described herein, nor do they endorse, recommend, or approve any such product or service.

We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept”, you consent to the use of ALL the cookies.
Do not sell my personal information.
Cookie SettingsAccept
Manage consent

Privacy Overview

This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary
Always Enabled
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
CookieDurationDescription
cookielawinfo-checkbox-analytics11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional11 monthsThe cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy11 monthsThe cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytics
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.
Others
Other uncategorized cookies are those that are being analyzed and have not been classified into a category as yet.
SAVE & ACCEPT